Friday, August 09, 2019

Three Investing Adages That Are Not True

Adages are fascinating, they are beautiful and usually true. Take everything in moderation, it's universal. There is no example one can think of when this phrase doesn't work. Or better safe than sorry. It's common sense but unfortunately, also commonly forgotten. It is also the basic tenet of investing - don't lose money, look for a big fat margin of safety. That's how we make money. 

But not all adages are true.

I have had problems with the following three, the more I think about them, the more I believe they are not true. Well, to be more specific, I think they are probably not true more than half the time. Yet, there are many who would believe in them. It then reflects their nascent thought processes and maturity in the markets. Would you agree?

1. Those who can do, those who cannot teach.
2. There are lies, damn lies and statistics.
3. Don't catch a falling knife.

Ok let's start with the first one. How many times had we learnt this phrase. But as I come across this phrase time and again, I must say it is only true maybe 10-20% of the time. Teaching is a noble profession. It is as good as any other profession. It takes a certain character and special skills to be a good teacher, a good coach. A good teacher understands how to motivate others but also needs to discipline, inspire, teach and lead. How many of us remember our best teachers? Think about how they have motivated us to be our best. Every great sportsman or sportswoman had a great teacher, a coach.

The world's greatest investor Warren Buffett had Benjamin Graham, his teacher at Columbia Business School. There are also many historically inspiring teachers, Aristotle, Helen Keller, Maria Montessori and in recent times Jack Ma and J.K.Rowlings were also teachers before they became famous in other fields. Warren Buffett said it himself, if he didn't become an investor, he would have been a teacher.

Of course there are teachers who are real CMIs*. But that's likely because they were pigeon-holed into the wrong profession. They simply needed to do a lot more to be a better teacher. It is sad because when a teacher cannot perform, it pulls down a bunch of kids. Unfortunately, most education systems have rigidity that is not able to help these teachers nor the kids.

*CMI = cannot make it, used as a noun 

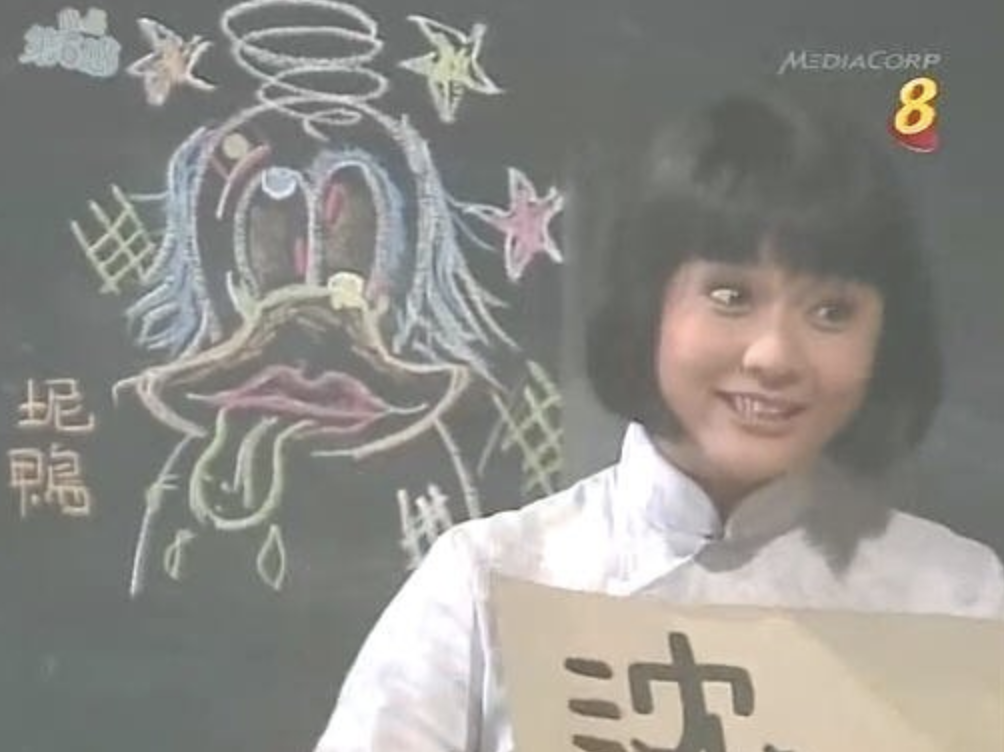
Scene from popular Singapore serial drama dedicated to teachers - 早安老师

It takes a lot to be a good teacher. Perhaps more so than an investor. So, it's not true that those who cannot teach. Good teachers can both do and teach. They are also the important human catalysts for creating future leaders and entrepreneurs. For Singapore to continue to progress, we need to make sure we attract the best to be our teachers. We can start by paying them well and stop them leaving schools and becoming tutors.

Interestingly, the second adage was made famous by a teacher - Mark Twain. Although he attributed the quote to the then British Prime Minister Benjamin Disraeli whose exact words were, "there are three kinds of lies: lies, damned lies and statistics."Yes, statistics can be used to lie, but data and statistics is the fundamental foundation of any analysis. To say that statistics are lies reflects the shallow thinking of the sayer. It is as good as saying aeroplanes are bad because they can be used by terrorists to crash into buildings.

Data, numbers and statistics are at the heart of value investing, or rather, any kind of due diligence. We rely on numbers and reading through the numbers to get to the truth. Yes, oftentimes, we need to question the numbers, slice and dice it differently to see the picture. But it doesn't mean statistics are lies. If there is any doubt that the people who created the statistics lack integrity, then we can no longer analyse the numbers and we need to change the people. Statistics are not lies. Statistics are tools. They are neither good nor bad. It is important to learn to use them well.

The normal distribution, the biggest subtopic in statistics

Okay and here's the most interesting of them all, "Don't catch a falling knife."

When I was a newbie investor, I totally believed in this. It just sounded so true. When the stock is going down, why would a smart investor want to buy it? Why catch a falling knife? But as I looked back at my investments over the years, this adage began feeling wrong. Even the analogy is wrong. A falling knife would eventually fall to the ground and lay still. But a stock, especially a good stock, would eventually go up. If you had done your work, calculated the intrinsic value of the company, understood the strong economic moat of the company, then you should buy when it's cheap enough. It doesn't matter if the stock is falling or rising.

We want to think we are smart enough to catch the turning point. We buy when the stock had turned up, when the knife is no long falling. Seasoned investors would know that's not possible. This adage plays different tricks to our minds and confuses everything. It assumes we can predict when stock prices had bottomed and would go up, it projects images of suffering huge pain caused by buying falling stocks. The truth is, we can always just buy a toehold position.

We cannot predict stock prices just like we cannot predict the weather. To not catch a falling knife when buying stocks is like never bringing an umbrella outside because we assume we will always only go outside on sunny days. In my mind, this last adage - never catch a falling knife is probably more harmful than helpful to investors. It sounds beautiful, logical and right. But, in reality, it's not.

Howard Marks

This truth also dawned upon me just recently when Howard Marks made it clear himself. Here's an excerpt of an interview about his views on falling knives. Obviously, he said it much better:

Marks: You mentioned catching falling knives, and my vision is that when the stuff hits the fan and there’s blood in the streets most people go like this, they say well we’re not going to buy until the knife stops falling, until the dust settles, until all the uncertainty has been resolved. But the trouble is that once that happens then the price will have rebounded. So we want to buy at a time of upset and while the knife is still falling and I think the refusal to catch a falling knife is a rationalization for inaction. It’s our job to catch falling knives, That’s how you get bargains. But you have to do it carefully.

So, next time someone tells you about not catching falling knives, you know he's a newbie. Tell him or her that our job is to catch falling knives, with gauntlets on. Some of us even have the Infinity Gauntlet. Stones and all. We time-travelled to enough alternative universes collecting Infinity Stones. If we want, we snap our fingers and the knife disintegrates. Refer him to this post and see if he agrees. 

Happy National Day! Huat Ah!

Sunday, July 28, 2019

Thoughts #16: Lessons from Serena Williams' Coach

Patrick Mouratoglou (born 8 June 1970) is a Greek French tennis coach and sports commentator. He has been the coach of Serena Williams since June 2012.

 My coaching method, which I apply to everyone, involves learning to understand the player, how to speak to him/her, how to analyze that player’s game and how to work with each of them taking into consideration their particular personality. I used to say that every player has their own world and their own language, and this is something you need to learn as a coach in order to be heard, trusted and followed.

More coaching tips:

Get input from your athletes - check with your athletes to determine if what you are communicating to them is understood, what they need, and what they want. Remember, if you are asking for input, at least be willing to incorporate something (a suggestion) at some point.

Keep your athletes informed as to when, where, how, and why (and WHY is most important) - people are not generally motivated to start (or finish) a task that is not clear in terms of when, where, how, or why. Take away any questions or doubts that your athletes may have by clearly and consistently communicating your expectations and intentions. Be clear as to when, where, and how . . . but most important, be sure your athletes know "why" they are being asked to do something. 

Create an environment that allows for challenge, recognition, appreciation, and quality - some of your athletes will be motivated by a challenge, some by recognition, some by appreciation, and some by quality of performance. It is important to know your athletes and what their primary motive might be. 

Challenge some (1 v 1 against a teammate), recognize others in front of their teammates (at the end of practice or in the locker room), appreciate others in private (in your office or the hallway), and provide others with a chance to show you a quality performance (quality over quantity of work). Remember, different athletes are motivated by different situations and feedback.

Give your athletes a reason to want to work hard - take the time to develop genuine, honest, caring, and trusting relationships with your players. Athletes will work harder (and longer) for someone they know genuinely believes in them, cares about them, and is committed to helping them achieve their potential. At the heart of player motivation is the quality of the coach-athlete relationship.

Model what you want to see - be motivated yourself. If you want someone to work hard, you better be working hard. If you want someone to put in extra time, you better be putting in extra time. Athletes do what they see. This is why the motivation of the coaching staff is so important and why it is so important to have quality team leaders who can lead by example, hold accountable, and promote a climate of motivation and inspiration. Set a motivational "standard" by what you do, say, and expect. Say it, expect it, but also make sure you do it!

Friday, July 19, 2019

Activision Blizzard - Part 1: Investment Thesis

Gaming has become part and parcel of everyday life no thanks to casual mobile gaming that had captured the eyes and minds of people young and old. The industry, segregated into mobile games, PC, console and others, is today a USD140bn industry which is larger than Hollywood and music combined.

What's more, the growth is accelerating. Esports, games with millions of spectators watching professional gamers play against others, is set to grow as big as traditional sports. This comes with it ticket sales, sponsorships, advertisements and merchandise purchases which would also serve connect the internet and real lives.

Esports gonna be as big as soccer!

At the core of it all stands two companies: Tencent and Activision Blizzard. Okay, maybe not just these two, but they are definitely up there on the league table alongside Electronic Arts, Nintendo, Microsoft (Xbox), Sony (Playstation) and dare I say, Razer, our homegrown mouse powerhouse! Today, we are going to do some deep dive analysis into Activision Blizzard (ticker code ATVI).

Investment Thesis

ATVI is one of the leading gaming company in the world having grown its franchises over the past twenty years across different eras, genres and gaming devices. Today, it boasts 345m monthly active users (MAU) across 8 blockbuster titles including Warcraft, Overwatch, Call of Duty and Candy Crush. Some of these titles has also established esports leagues and ATVI stands to benefit as esports take off in the near future. It also boasts strong track records in both innovation and M&As and should continue to produce and acquire new esports franchises in the future.


ATVI has consistently generated positive free cashflow and analysts had estimated that it could generate USD 2.2 to 2.5bn in FCF in the next three years and likely grow to USD 3bn in the future. As such, at its market cap of USD 32bn today, it would mean that ATVI is trading at 6.9%, 7.8% and 9.4% FCF yield respectively. This represents significantly margin of safety for a gaming leader with strong branding and strong franchises.

So, in essence, that was the investment thesis for ATVI. The investment thesis is the reason why we want to buy a stock. It should be easily articulated and remembered. Then as we research further, we should identify the supporting positive factors and also the risks. In the next few paragraphs, we would describe industry background, business model and the positives for ATVI - brand stickiness in gaming and how it further enhances AVTI's moat surrounding one of the most solid business models on our planet.

Gaming's beginnings and business models

The gaming business started in the late 1960s and early 1970s with arcade games which later evolved into console gaming and now mobile and multi-device gaming. We are also catching glimpses of the future - game streaming, just like what Netflix did for movies and Spotify for music. The business model has a recurring income stream since the days of console gaming. This was the famous razor-blade model whereby users paid up once for razor (the console) and then made further recurring payments for the blade (the games which used to cost $20 but are now costing $50 to $70!). In game streaming, this revenue stream gets further stability as each gamer pays a monthly subscription just like today's Netflix and Spotify users.

The original Gillette razor and razor blade


In the last 50 odd years, scientists had studied gaming thoroughly and had seen the impact on human brains. In short, gaming is a form of addiction, just like smoking, alcohol, drugs, sex, casinos, chasing Korean drama, Facebook and reading investment blogs (just kidding). In the spectrum of various addictions, it is probably not as bad as casinos or smoking but it's definitely worse than losing sleep chasing Korean drama or constantly checking Facebook and neglecting your family. Games are now designed specifically to entice with cues that would trigger desirable actions which would then lead to rewards. This releases dopamine into our brains, making us feel good and hence constantly seeking to replicate this cycle.

In casinos with the slot machines, the cues would be the near misses such as lining up two sevens (while three sevens would mean hitting the jackpot) that would trigger the gamer to keep pulling the slot lever (hence burning a lot of cash along the way). Once in a while, three fruits (not three sevens) would line up and reward the players with a small payout, keeping them hoping for more. Over hours, days, weeks and even years, pathological gamblers become stuck and would squander all their monies and go into debt, leaving their lives in ruins. As this became clear, governments started regulating casinos.

Mobile or console gaming, today is not regulated. Well, first, most gamers do not spend enough to go into debt. But games work with the same principles: cues, triggering actions which sometimes lead to rewards. For instance, Candy Crush, gamers would quickly find out that it happens very often that they will run out of moves and very coincidentally, only one more move is needed to complete the level. To complete the level, one would have to fork out $1.99 for that one move. This is very powerful and 3-5% or sometimes more of the population ultimately falls for it.

Out of moves!

There are many more well research cues that game designers use to ensure that gamers come back for more. We discussed near misses, there's also level progression, rankings, competition with friends, rewarding gamers with awesome story graphics and ending scenes, rare collectors items in games and many more. Guess what, Activision Blizzard knows them all and had been using these for years.

Brands

In one of their most successful games - World of Warcraft, the average gamer spend a crazy 22 hours per week in the game. Almost 30% of players play more than 30 hours per week. That's 6 hours from Monday to Friday. In most CBD* jobs in Singapore where white collar workers do 90 minute lunches and multiple coffee breaks, the hours on Warcraft spent beats full-time job hours. Maybe some CBD workers are spending lunch and coffee breaks playing World of Warcraft.

ATVI understands games better than anyone else. But it also understands branding and marketing. The company had successfully generated so much hype for most its top franchises that almost always guaranteed sellouts. In one recent instance, Call of Duty - Ghost sold USD 1 billion dollars on its first day. As such, ATVI boasts eight billion dollar franchises namely: Call of Duty, Warcraft, Overwatch, Candy Crush, Diablo, Starcraft, Heartstones and Skylanders. It constantly rotates new sequels amongst these franchises not unlike what Disney is doing with Marvel, Star Wars, Pirates of the Caribbean, Indiana Jones, Pixar and more recently remakes of old Disney cartoons. This strategy generates some stability in an industry with constant hits and misses.

As such, in recent years, we had seen strong and growing free cashflows (in both Disney and ATVI). In the next post, we shall discuss the other positives and risks. Huat Ah!

*CBD stand for Central Business District.

Monday, July 08, 2019

Charts #23: True Cost of Your Cup of Coffee

Enlightening cost breakdown by FT
2.50 pounds is c.S$4.40


35% Shop cost/rent
25% Staff cost
15% Tax and additional costs
10% Profit
7% Cup, napkins, stirrers
4% Milk
4% Coffee

We are not paying for coffee!


Saturday, June 29, 2019

2019 Dividend List: 10 Years On

We started this dividend list in 2009 and in a blink of an eye, ten years flashed past. The list had since gone global as there are just that many (or few) dividend stocks in Singapore. Some of them had been bought out, some just weren't strong businesses to begin with and faltered and some others go in and out of the lists and a handful of names remained in it to this day. 

Last year, we dissected global dividend companies and discussed a few interesting names: Coach, Cisco, advertising companies. We see some of the same names this year and sadly, there isn't really good names or stories to share. The list tend to capture past business models with no growth such as brick-and-mortar shops without the new crowd drawing experiential retail innovation like Escape Room, Kidzania etc. I believe this is the key limitation of this list after looking at it for ten years. It spits out past business models and also fails to capture the exciting companies like Google, Live Nation and Netflix.

Well, that's value investing though, we want things cheap, so they don't come without caveats. Most would be cheap for some reason and once in a while we can find a gem. Here's this year's first few names:

2019 Dividend List - Part 1

This year's list featured the same retail and tobacco and old economy companies such as Evraz, a steel company that's at the top of the list. It's probably in a distress situation and the 15% dividend is unlikely to be sustained. Rio Tinto is not about to go bust, so it could be a candidate. Although I always like BHP with its pole position and better diversification across different commodities. So besides Rio, there isn't another name that I am keen to spend more time doing desktop research.

2019 Dividend List - Part 2

The same could be said for the second portion. These are another bunch of old economy names with the more interesting ones all discussed in the last few years: Harley Davidson, Tapestry, IBM and Western Union. BAE systems could be the only stock worth more research given the interest in defense growing as China and Russia try to strengthen their military might to compete with the US. North Korea could also turn belligerent again, who knows. But BAE might have its own issues for the stock to appear here. Or it could just UK's issue again. Given how the Brexit risk loomed larger this year, it's no wonder that this list featured so many UK stocks.

Given the paltry list this year, I thought we could relook at some of the interesting Singapore names. They are no longer featured because of either valuations or margins. To pass the screening, companies need to have FCF yield of more than 4.5% and margins of 8% and sadly, 1-2 Singapore companies failed the margin test while those with high margins are not cheap enough (hence failing the FCF yield criteria). Then, there are some who failed to ROE test (must be more than 10%) as they hold to much cash or equity, which dampens the ROE.

Nevertheless, here's my own curated list of the top dividend stocks in Singapore. I have held some of these for more than a few years and they had generated good dividend return (but unfortunately not too good capital return). So these are ideas for anyone trying to build a dividend portfolio but do your due diligence and double check on valuations and make sure you have a good margin of safety. 

Of the stocks in the list, I would think only Overseas Education would be worth buying today, but it's a micro-cap and there are different risks and considerations as well e.g. liquidity and getting taken out cheap if there's a management buyout.

1. SIA Engineering: Dividend 4.8%, Singapore Airlines' maintenance arm.
2. Vicom: Dividend 6.6%, largest vehicle testing and inspection company.
3. SGX: Dividend 4.8%, Singapore's stock exchange.
4. Overseas Education: Dividend 8.8%, international school in Singapore.
5. ST Engineering: Dividend 3.6%, defense and aerospace, also competes with SIA Engineering.
6. DBS: Dividend 4.7%, Singapore's largest bank.
7. Singtel: Dividend 5.1%, used to be Singapore's largest company. Looking to divest out of this. Wouldn't recommend anyone to buy now.

Friday, June 21, 2019

Thoughts #15: Esther Wojcicki's Wisdom

Esther Wojcicki is a panda mum (opposite of Tiger mum) who raise three successful girls who are changing the world as we speak. The eldest, Susan is head of YouTube. The second, Janet is a famous anthropologist and the third Anne founded 23andme - a DNA analysis startup.

Her key message to parents: just relax. Trust your kids to learn well. Her definition success: Being happy with yourself and happy with what you have achieved, and having some kind of goal in life. It should be the same wish for our kids. We wish they are happy and they achieved something meaningful at some point and continue to have some kind of goal in life.

Simple right?

No need to worry about streaming, PSLE, which university they can go, who they marry, what kind of job they would end of with. Just relax...That's how she raised three successful girls and they in turn want to repay her and bring their beloved mother to parties and tours so that she can enjoy.

And here's the irony and the punchline:

“I have been on more yachts than you will ever be on in your life. I have been on more private beaches, more private islands. And guess what? I like being with the regular people more. I like being on a regular crowded beach and watching everybody walk up and down. I find that more interesting.”  

Last but not least:

Ms Wojcicki’s take home message for parents, which is: “Have a good time with your kids. When you have a good time, they have a good time. Life is an opportunity to have fun, why not do it?”

Monday, June 10, 2019

Charts #22: Another Property Chart

Here's another city property chart that looked interesting. How much space can USD 1m buy? Does it really make sense? The record is now held by Monaco at 16 square metre. This is not to say property is a bad investment though.


If we think about it, this is just another greater fool game in a different scale, or as we had discuss, the reflection that the value of money will just keep getting eroded with inflation and QE. If we look at this chart in twenty years, maybe Monaco will be 8 square metre and the rest of the cities will see some positions swapped. The last city will also be much smaller than the 200 square metre listed here.

Saturday, June 01, 2019

Lessons Learnt: Hyflux - Part 2

This is a continuation of the previous post.

In the last post, we summarized the Hyflux debacle and discussed the lessons learnt.

1. Always limit or risk capital to an amount we can lose
2. Map out all the scenarios and probabilities and keep monitoring them.

Today we delve in #2 and share the third and fourth lessons further below. In our due diligence on Hyflux eight years ago. I would say that I did not do this well. Hyflux scenarios and probabilities should have looked like the following:

60% - business as usual, Hyflux continued to operate as successful as it had since IPO. In this scenario, things pan out as we wanted, perp holders get back their money when Hyflux redeemed them in 2018 or 2020. This would be the base case or good scenario.

30% - Hyflux business deteriorates or the external environment changed, causing some cashflow problems. But Hyflux should manage to pull through either with bank credit lines or with the Singapore government awarding it yet another project. Or Hyflux raised equity or debt to fund itself.

As a side note, this was partially played out in 2016 when it raised yet another round of perps. It should have served as a warning sign, but back then, no one suspected anything. Hyflux was going strong and Tuaspring was touted as a gamechanger. 

10% - Hyflux fails for some reason. This is the worst case or disaster scenario. In Hyflux's case, this scenario is playing out now. 

Investors complaining Hyflux's epic failure

In my analysis, I did not pay attention to this last scenario. I would never had ascribed a 10% probability of failure at that time. But maybe it should be a 1% or a 5% probability event. I should have considered it. Let's for learning sake mapped out how things would be like if I had ascribed such a scenario. Say, we ascribe a remote scenario that Hyflux would fail. The probability that Hyflux would fail is higher than say, DBS or UOB would fail. Then logically it means that 6% is not good enough. This was because DBS or UOB perps were at 5%. Between Hyflux at 6% and DBS at 5%, which investment is better? I would say DBS.

Inverting the thinking a bit, the question should also have been asked clearly: at 6% yield, we get back our capital after 16.7 years. Will Hyflux fail in the next 16.7 years? Hard to say but if it happened would this still be a good investment? The answers are clear on hindsight, now that things had happened. It would be hard to answer these back then, but still, these questions ought to be asked. It could meant a different decision: not to invest at all, or bid lower and put less capital at risk, or maybe buy DBS perps instead.

There was also a lot hype when the offering was launched. It was way oversubscribed and hence such risk hedging thoughts were thrown out of the window. So, on hindsight, there is a sub-lesson here (which again, we already know): the crowd is not always right, be fearful when others are greedy.

The other mistake was also the lack of monitoring. After I bought these, I was just happily receiving coupons and occasionally read some annual reports and followed the news. That's it. I didn't even know Hyflux issued more perps in 2016 until a few months later. Then when things really turned south, I still wasn't monitoring as hard. This brings us to the third lesson.

3. Act fast don't hope

As things deteriorated. I held hope that Hyflux could turn around. The perp prices fell from 80c to 50c to the dollar. I could have sold! That way, with the coupons clipped over the years, I would have lost a mere 10-20% of capital rather than 60%. This would prove to be a lesson that I had not learnt well. I had never cut loss well. I cut losses only to see stocks rebound 50% and fail to cut those that go down a lot more. It would likely take more years to hone this skill better.

Hope is a dangerous thing

This has to do with judgement. In Hyflux's case, we had determined that the business model was flawed. It needed to bid for projects and cost overrun could be very detrimental. When they issued another perp in 2016 and when the initial warnings came, I should have paid more attention. Judgement can only be honed over time and experience. It is also about understand the business model, the situation and all that is at stake. When the bond prices finally reacted and fell to 50c, it was supposed to be a big warning. Yet I failed to do more detailed due diligence. It wasn't my priority until everything blew up. Hence there's a last lesson here from Hyflux.

4. Focus on the best businesses

Investing is a full time job. If you want to make money, you have to devote the time and effort. But in today's world, where got time? We have our day jobs, family, kids, friends, social and community activities. It's just so difficult. This is so even when I am passionate about investing. Imagine someone who is not passionate but wants to invest because he or she thinks it's good passive income, easy money.

So in order to be able to invest and sleep well, we can only buy the best businesses because we don't have time to monitor any deterioration. Having said that, good businesses also get disrupted and we need to stay on top of things when we see these happening (Singtel, which I have, comes to mind). If we buy the best businesses, those with strongest economic moats which we had discussed before, generating strong free cashflows at reasonable valuations, then our capital would have more protection. 

In conclusion, here's the four lessons again from the Hyflux debacle:

1. Always limit or risk capital to an amount we can lose
2. Map out all the scenarios and probabilities and keep monitoring them.
3. Act fast don't hope
4. Focus on the best businesses

Hope this would help us avoid future debacles, huat ah!

Saturday, May 18, 2019

Thoughts #14: Hwa Chong or Chinese High?

Are you Hwa Chong or Chinese High? This was a perplexing question for some who attended these schools in the late 1980s and early 1990s. Hwa Chong Junior College (a.k.a HCJC, a prominent high school in Singapore) was established which was a separate entity to the Chinese High School, one of the earliest boys' school in Singapore.

The story goes that Chinese High organized a 100th anniversary dinner in March 2019 and if you are a Hwa Chong student, it's technically not your dinner. So should you attend? However, HCJC was then merged with Chinese High to form Hwa Chong Institute when the through train program was introduced. In short, HCJC ceased to exist and there would be little reason to hold HCJC only dinners in the future.

But from the perspective of proud HCJC students, it's an important segregation. Partly because either they came from other reputable secondary schools (junior high schools) and would want to associate more with their alma mater of four years (since junior college was only two years) or they simply did not want to associate with Chinese High (especially ladies, since this was a boy's school).

In the end, it all boils down to time and perspective. Another 100 years from now, would anyone remember there was this segregation between Hwa Chong and Chinese High? Would anyone care? Flipping things around, would anyone of us here be around to attend the 200th anniversary dinner? If not, then should we attend this one? What would happen if we missed this dinner? It is regret or no big deal? 

Investing is also about asking the big questions. Some of the big questions that I like to ask are:

1. In 5 to 10 years, how would this bad news affect the stock? Is it a critical bankruptcy blow? What is the likelihood that the company ride through this and become stronger?

2. Does this action survive the "newspaper headline" test? (this is both an investing and life option question, when we do something questionable, think of how it would look if the media looks at it.)

3. What happens if I am wrong? What is the maximum loss? Can I sleep soundly at night holding this mistake (if it turns out to be one)? Does it mean critical financial damage? 

Another analogy worth sharing: Omaha Beach in Normandy, France was one of the bloodiest fighting spots during D-Day, 6 June 1944. Thousands of Allied soldiers sacrificed on that day to secure landing sites in order to topple Hitler. They succeeded. As Asians, we would probably shun buying any properties there in the 1950s, given the risks of haunting and what not. But, today, it's expensive beachfront properties. Who cares about D-Day. It's all time and perspective! 

Happy Vesak Day!

Friday, May 10, 2019

Lessons Learnt: Hyflux - Part 1

Eight years ago, we discussed Hyflux perpetual bonds here, putting forward the investment thesis that 6% was good dividend/interest income and how Hyflux had a so-so business model but things should be okay because the Singapore government would support Hyflux as they had done so in the past. That turned out to be a huge mistake. Not only did the government not support Hyflux, she rubbed it in, pushed the proverbial dagger into Hyflux's belly, delivering the fatal blow.

Et Tu Temasek? (Ref: Et tu Brute)

How did things come to such a dire situation? 

As described in the post eight years ago, Hyflux's business model relied on winning water projects, which meant that they had no control over the bidding price and also, in subsequent years, their own future revenue. However, as with most Singapore co.s, we are good at managing costs, which allowed us to beat many others in the global game of winning EPC (Engineering, Procurement, Construction) contracts. This was how Keppel and Sembcorp became so good in oil rigs.

But in order to grow, companies in the EPC field have to bid for bigger and bigger projects. The cost management however gets more and more complex. Once every decade also, someone would definitely screw up and one or two badly designed contract put EPC firms at risk of bankruptcy. Alas, Hyflux was not spared.

Tuaspring, Hellspring

The irony for Hyflux was that the contract turned out to be one in its home country. This was infamous Tuaspring desalination project. Tuaspring became a bomb because of its large scale and complexity. The Achilles' heel in Tuaspring is actually not desalination but power generation. For reasons unclear to me now, someone thought it's a good idea to combine the two. Maybe because desalination requires a lot of power, so hey why not generate power, then sell some power plus water to PUB as well. This definitely developed as the logical train of thought from our admin officers in the civil service and Hyflux went along.

But selling power is not the same as selling water. Cost for selling power depends on fossil fuel, the most important being crude oil, which is notoriously volatile. Meanwhile, power prices in Singapore collapsed as a result of energy deregulation. So suddenly, Hyflux found itself caught in a situation where its power generation cost exceeded its revenue. With a billion dollar debt on its balance sheet, things quickly spiralled downhill. Our admin officers don't give chance these days, just like the new Certis Cisco summon officers.

Hyflux began to run out of options as credit dries up and in an "unthinkable" scenario for investors who put in money in 2001 during its IPO to yield chasers (like me) who bidded to buy its perps in 2011 and more yield chasers who bought its perps again in 2016, Hyflux declared it might go bankrupt. A white knight from Indonesia (Salim group) appeared, willing to put money to save the firm but not the perp bondholders. Alas, that hope is now also gone as PUB decided to push the dagger some more (figuratively impaling Hyflux now), terminating Tuaspring water purchase agreement. 


As things stand, it is likely that bondholders and shareholders will get nothing in the end, barring some kind of miracle. It's neither Oliver Lum's nor PUB's fault. This is just investing. There's always risk. Perils on top of perils. Caveat Emptor.

The saving grace for those of us who invested in 2011 though was that we got a few years of 6% coupon. Not great, as the total loss of capital was still north of 60%. But almost everything is now bridge under the water. So this post serves to help us learn the lessons and move on. Well, it's mostly re-emphasizing the importance of what we already know:

1. Always limit our risk capital to any single name to an amount that we would be okay it if goes to zero. This could be an absolute amount and it could be a percentage of total net worth. What's important is that we can sleep at night. We hear stories of people who put in $200,000 or $300,000 into Hyflux perps and that's a huge chunk of their retirement nest egg or net worth. It's just so sad. So don't make this mistake.

2. Map out the scenarios and probabilities well and keep monitoring them. When we did the due diligence in 2011, we determined that the business model was flawed, one project could kill them. But we also thought that the Singapore government should come and bail them out. After all, this was Singapore's poster child. Little did we expect it would be the opposite! The project was in Singapore and the government delivered the fatal blow! Nobody could have foreseen this. But, on hindsight, we should have put in a scenario that Hyflux would go bust and ascribed a probability. In the next post, we should delve into this!

Caveat Emptor: Let the Buyer Beware!